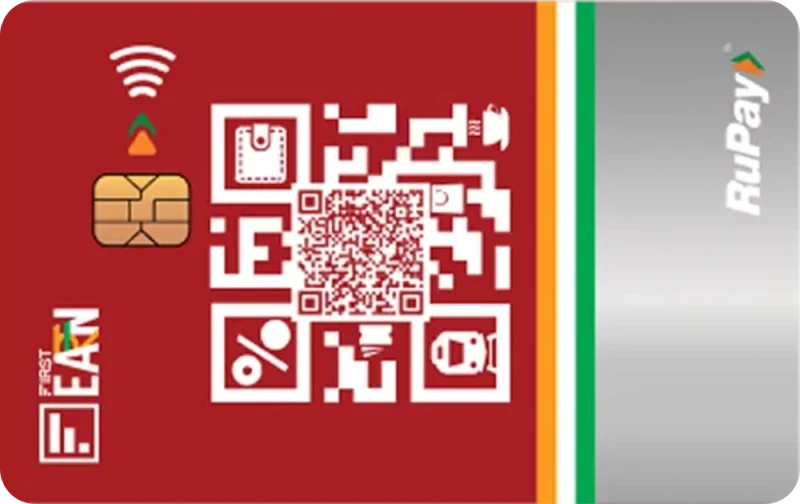
IDFC FIRST EARN Credit Card benefits
- Rewards1%
cashback on UPI payments through the IDFC FIRST Bank app
- Rewards0.5%
cashback on other UPI apps, online spends and bills
- Rewards
Cashback up to ₹500 a statement cycle
- Deposit
Issued against a fixed deposit from ₹5,000
with no credit history needed
- ForexZero
forex markup
Good to know
- Annual fee ₹499, waived on ₹1 lakh of yearly spends
IDFC FIRST EARN Credit Card rewards and cashback
| Where you spend | Rate | Monthly limit |
|---|---|---|
| Everything else1% cashback on UPI payments made through the IDFC FIRST Bank app, within the same ₹500 limit a statement cycle. Left out of the maths because it depends on which UPI app you use. | 1% back | 500 |
| TravelUp to 5.5% on hotels and 2.5% on flights booked through FIRST Rewards Gallery in the IDFC FIRST Bank app, with up to ₹2,000 of bonus cashback a month. Left out of the maths because it applies only to bookings in the app. | 5.5% back | 2,000 |
| Everything else | 0.5% back | 500 |
No rewards on: EMI and cash withdrawals.
All reward rules
- 0.5% cashback on UPI payments through other apps such as Google Pay, PhonePe, Paytm and CRED, on online spends, and on utility, insurance and wallet load payments.
- All cashback is capped at ₹500 a statement cycle. This is a virtual card, so it works for online and UPI payments, not card swipes in shops.
- 0.5% cashback on international spends, with zero forex markup.
- Joining offer: 10% cashback up to ₹250 on your first transaction.
- 25% off up to ₹100 on movie tickets, once a month.
- Utility spends above ₹20,000 in a statement cycle attract a 1% fee, and rent payments a 1% fee of at least ₹249.
What the IDFC FIRST EARN Credit Card gives back in a year
Say you spend ₹30,000 a month, like our “online shopper” pattern. Worked out with the same maths as the calculator above.
| Spending | A month | Back | A year |
|---|---|---|---|
| Groceries | ₹3,000 | 0.5% | ₹180 |
| Dining and food delivery | ₹2,000 | 0.5% | ₹120 |
| Online shopping | ₹18,000 | 0.5% | ₹1,080 |
| Travel | ₹1,000 | 0.5% | ₹60 |
| Fuel | ₹1,000 | 0.5% | ₹60 |
| Bills and utilities | ₹2,000 | 0.5% | ₹120 |
| Everything else | ₹3,000 | 0.5% | ₹180 |
| Total | ₹30,000 | ₹1,800 | |
| Renewal fee with GST | Waived | ||
| You keep | ₹1,800* |
IDFC FIRST EARN Credit Card annual fee and charges
- Joining fee
- ₹499
- Annual fee
- ₹499
- Fee waiver
- ₹1,00,000 a year
- Foreign currency markup
- 0%
Joining fee ₹499 and annual fee ₹499 from the second year, both before GST. IDFC FIRST Bank currently charges ₹0 joining fee as a limited period offer. The annual fee is waived on ₹1 lakh of yearly spends.
IDFC FIRST EARN Credit Card eligibility
- Age
- 18 to 80
- Lowest fixed deposit
- ₹5,000
The card is issued against a fixed deposit with IDFC FIRST Bank, starting at ₹5,000, and your limit equals the deposit. No credit history is needed.
The bank alone decides approval and your credit limit.
IDFC FIRST EARN Credit Card lounge access
The bank's terms list no fixed number of free airport lounge visits on this card.
Is the IDFC FIRST EARN Credit Card right for you?
A card with a ₹499 fee that spending can waive, paying a below-average 0.5% on most spends.
Worth its fee if you spend about ₹9,000 a month or more. Below that, the ₹499 fee costs more than the card gives back on spending like the example above.
Good for you if
- You spend ₹1,00,000 a year or more (about ₹8,400 a month), so the ₹499 renewal fee is waived.
- You pay in foreign currency, abroad or on foreign websites: the markup is 0%, against a typical 3.5% on the cards we list.
- You have no credit history or a low score: the card is issued against a fixed deposit of ₹5,000 or more.
- You pay by UPI: it is a RuPay card you can link to UPI apps and use at shop QR codes.
Not for you if
- You spend less than about ₹8,400 a month: you would pay ₹589 a year with GST.
Check the latest fees and terms on the bank's page before you apply.
Alternatives to IDFC FIRST EARN Credit Card
Two similar cards to weigh up before you apply. The last column shows what each may be worth on ₹30,000 a month of mixed spending, after the renewal fee with GST. Rates paid only at named brands are not counted, so a brand card can earn more if you shop there.
| Card | Annual fee | Rewards up to | You keep a year |
|---|---|---|---|
| IDFC FIRST EARN Credit Card | ₹499 | 5.5% | ₹1,800* |
| IDFC FIRST Hello Cashback Credit Card | ₹1,000 | 3% | ₹5,160* |
| Kotak 811 Dream Different Credit Card | Free | 2% | ₹2,880* |
If most of your spending looks like the example above, the IDFC FIRST Hello Cashback Credit Card may suit you better: it would leave you ₹7,800 a year, against ₹1,800 with the IDFC FIRST EARN Credit Card.
*Estimate only, not a promise. We work it out from the bank's published terms and the spending you enter. What you actually get depends on the bank, your transactions and any change in its terms.
Frequently asked questions
What is the annual fee of the IDFC FIRST EARN Credit Card?
The joining fee and the annual fee are ₹499 each, before GST. The joining fee is currently ₹0 as a limited period offer, and the annual fee is waived on ₹1 lakh of yearly spends.
How much fixed deposit do I need for the FIRST EARN card?
At least ₹5,000 with IDFC FIRST Bank. Your credit limit equals your deposit, and you can link more deposits to raise it.
How much cashback does the IDFC FIRST EARN card give?
1% on UPI payments through the IDFC FIRST Bank app, and 0.5% on other UPI apps, online spends, utility, insurance and wallet loads. Total cashback is capped at ₹500 a statement cycle.
Can I use the FIRST EARN card for UPI?
Yes. It is a RuPay card that links to UPI apps such as the IDFC FIRST Bank app, Google Pay, PhonePe and Paytm.